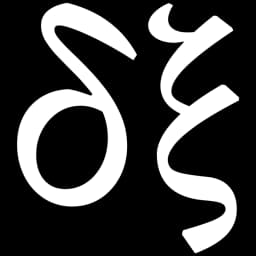
Expected shortfall
The average loss in the worst part of a loss distribution.
Library note. Check the assumptions and further reading before applying a formula.
What Is This?
A loss threshold tells you where bad outcomes begin. Expected shortfall asks how severe the outcomes beyond it are. L denotes loss, so larger numbers are worse. At a 95% confidence level, expected shortfall averages the worst 5% of the distribution. The integral definition also handles distributions with jumps, where a simple conditional average can be misleading.
Try an example
Suppose you have 100 equally weighted loss scenarios. To estimate 95% expected shortfall, average the five largest losses. If those losses are £4, £5, £6, £10 and £25, the estimate is £10.
Where it needs care
Rare losses are hard to estimate from a short record. The mean tail loss must exist. Expected shortfall says nothing about the order of losses, so inspect drawdowns and stressed paths too.
Historical Context
Expected shortfall became prominent in the study of coherent risk measures in the late 1990s and subsequent financial risk management.
Real-World Applications
- Compare the severity of modelled tail losses.
- Set risk limits alongside liquidity and drawdown constraints.