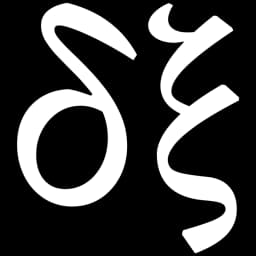
Itô's lemma
The chain rule gains an extra term for Brownian motion.
Library note. Check the assumptions and further reading before applying a formula.
What Is This?
Ordinary calculus tracks smooth changes. Brownian paths are too rough for its usual chain rule. If X follows a process with drift mu and noise scale sigma, Itô's lemma describes how a smooth function of time and X changes. The extra second-derivative term comes from the accumulated squared fluctuations. W denotes standard Brownian motion; subscripts on f denote partial derivatives.
Try an example
For f(x) = x squared and X = W, the rule gives d(W squared) = 2W dW + dt. The final dt term is the part the ordinary chain rule would miss.
Where it needs care
The displayed version assumes an Itô diffusion and a function with one continuous time derivative and two continuous spatial derivatives. Jump processes need additional terms.
Historical Context
Kiyosi Itô developed stochastic integration and its change-of-variables rule in the 1940s. It became a foundation of modern stochastic calculus.
Real-World Applications
- Transform stochastic differential equations.
- Derive models used in option pricing and diffusion theory.