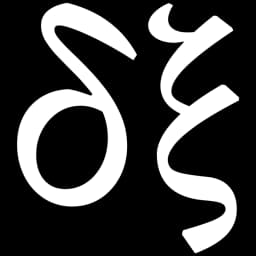
Maximum drawdown
The largest fall from a previous wealth peak.
Library note. Check the assumptions and further reading before applying a formula.
What Is This?
Drawdown measures how far a wealth path has fallen from its highest value so far. Maximum drawdown is the largest of those falls over the chosen period. Unlike a return average, it depends on the order of events. A strategy that recovers by the end can still put its owner through a deep loss along the way.
Try an example
An account rises from £100 to £120, drops to £90 and finishes at £110. Its maximum drawdown is 25%, measured from £120 to £90, even though it ends above its starting value.
Where it needs care
Assume positive wealth and adjust for deposits and withdrawals. Results depend on the date range and sampling frequency. The worst loss in a backtest is not an upper bound on future losses.
Historical Context
Peak-to-trough declines are a long-standing way to describe financial performance. They also arise in probability problems about running maxima.
Real-World Applications
- Compare the depth and duration of losses.
- Check whether a path would breach a contractual loss limit.